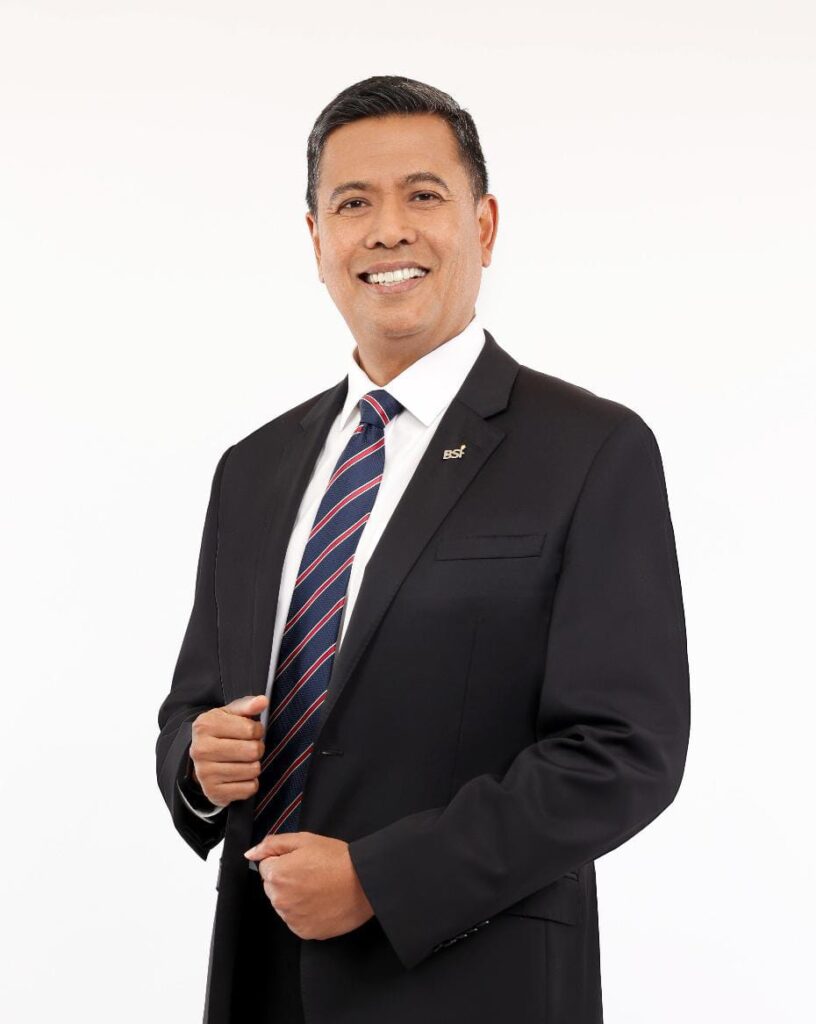
Aceh – Indonesia, Jakarta -. PT Bank Syariah Indonesia (Persero) Tbk (BSI) continues to accelerate rapidly with an increasingly solid fundamental foundation. Entering the third quarter of 2026, BSI recorded a net profit of IDR 5.30 trillion through August 2026, representing a 10.07% Year-on-Year (YoY) growth. This profit surge was driven by high-quality business expansion, stronger low-cost funds, accelerated financing, and growing contributions from its gold business and fee-based income. This performance highlights that BSI’s growth relies not only on asset expansion, but also on reinforcing its funding structure and enhancing its core business mechanisms.
Additionally, sound risk management, rigorous financing monitoring, and stronger Good Corporate Governance (GCG) implementation have supported the company’s vibrant business expansion amid challenging economic conditions.
On the funding side, BSI’s Third-Party Funds (DPK) surged 17.71% YoY to IDR 389 trillion, with low-cost funds (CASA) reaching IDR 246 trillion. The CASA expansion was primarily propelled by savings growth, which reached IDR 171 trillion, solidifying the funding architecture while improving the bank’s cost of funds efficiency.
This operational efficiency is reflected in the Cost of Fund (CoF), which dropped 37 bps year-on-year to 2.30%. The decline in CoF grants BSI room to maintain financing competitiveness while preserving profitability amidst dynamic banking industry trends.
Regarding financial intermediation, BSI’s financing grew even more aggressively. As of August 2026, total financing expanded to IDR 344 trillion, a 16.21% YoY increase—outpacing its DPK growth. This expansion demonstrates the company’s capacity to optimize liquidity to drive productive business activities while maintaining asset quality. Despite the rapid growth, BSI maintained strong credit quality control, evidenced by a low gross non-performing financing (NPF) ratio of 1.8%.
Further growth momentum stemmed from fee-based activities, as Fee-Based Income (FBI) soared 36.27% to IDR 5.6 trillion, boosted significantly by treasury operations and the gold business. This performance lifted BSI’s fee-based ratio to 23.07%, reflecting an increasingly diversified income base beyond traditional financing operations.
BSI President Director Anggoro Eko Cahyo stated that the company’s performance through August demonstrates that BSI’s business transformation is yielding balanced growth across funding, financing, and non-financing income lines. “We see BSI’s fundamentals becoming increasingly robust. Double-digit profit growth goes hand-in-hand with CASA strengthening, elevated financing expansion, reduced cost of funds, and accelerated fee-based income. This indicates that BSI’s growth engine is increasingly diversified with ample room for further expansion,” he said.
Heading into the late third quarter and fourth quarter of 2026, BSI will continue to reinforce its low-cost funding sources, which remain one of its primary competitive edges. Key initiatives include expanding the Hajj and Umrah ecosystem, alongside scaling up underlying-based consumer and retail financing known for resilient business characteristics.
Furthermore, BSI plans to propel the growth of the Sharia ecosystem and gold business, enhance digital transactions and services, and safeguard financing quality as part of its sustainable growth strategy. “Moving forward, our focus is not merely on growing larger, but ensuring that growth yields stronger quality and profitability. We remain optimistic that our Q3 and full-year performance will stay firmly on track,” Anggoro added.
Backed by a stronger funding structure, efficient CoF, double-digit financing growth, and an expanding fee-based income contribution, BSI enters the second half of 2026 equipped with a fully optimized growth engine and reinforced fundamentals.